Over-billings you cannot see
Money in the account against work you have not performed yet. It spends exactly like profit right up until the job closes out and the cash has to come back from somewhere.
Borrowed from the next job Pick a time
Commercial construction only
Thirty minutes with a construction CFO, on your open contracts.
Rather write first? Email contact@todaycfo.com.
The problem
A generalist opens the profit and loss, sees a good month, and reports a good month. The work-in-progress schedule can be saying something completely different at the same moment. If nobody produces it monthly, the first person to read it properly is your underwriter.
Money in the account against work you have not performed yet. It spends exactly like profit right up until the job closes out and the cash has to come back from somewhere.
Borrowed from the next jobTen percent held across several contracts, on release schedules that live in other people’s systems. Nobody in your office can say what the number is today.
Your profit, in someone else’s accountThree years of financials and a current work-in-progress schedule. If the WIP does not exist until somebody asks for it, the job you wanted is decided by paperwork rather than by your price.
Jobs you never got to bidFour sentences
Each one sounds like a paperwork complaint. Each one is a number. That gap is the whole of it, and it is why this stops being annoying and starts being expensive.
They are holding ten percent and I do not know what that adds up to.
That is your profit, sitting in someone else’s account, on a release schedule you have not been told. Across four contracts it is usually a bigger number than the owner guesses.
My pay app got rejected and I lost thirty days.
A G702 that does not tie to the schedule of values comes back, and the next billing window is a month away. You financed that month out of your own working capital.
I did the extra work, they never sent the change order, and now nobody wants to talk about it.
Work performed against an unapproved change order is cost with no revenue behind it. If it is not logged as performed and unapproved the day it happens, it quietly becomes a gift.
They want three years of financials and a WIP schedule. I do not have a WIP schedule.
That is a prequal packet coming back short, and it is the point where paperwork stops being annoying and starts deciding which jobs you are allowed to bid.
The call itself
Roughly what you have open, roughly what is held in retainage, and the last pay application that came back if there was one. Estimates are fine. Nothing gets pulled out of your accounting file for this.
Percent complete on your open jobs, what retainage adds up to across them, what is stalling your billing, and the accounting method your contracts are currently being reported under.
A straight read on whether your reporting is what is holding the business back, and what it would take to fix. If it is not, we say so on the call rather than book a second one.
The Financial Risk Assessment. Free, 86 checkpoints on your real books and your real contracts, with a findings call at the end. It is a required step before either side agrees to work together, and the findings are yours either way.
Before you book
What running with us looks like
Every client, at every level, gets the same page every month, by the eighth business day, and it gets walked through with you on a quarterly call.
Who you are talking to
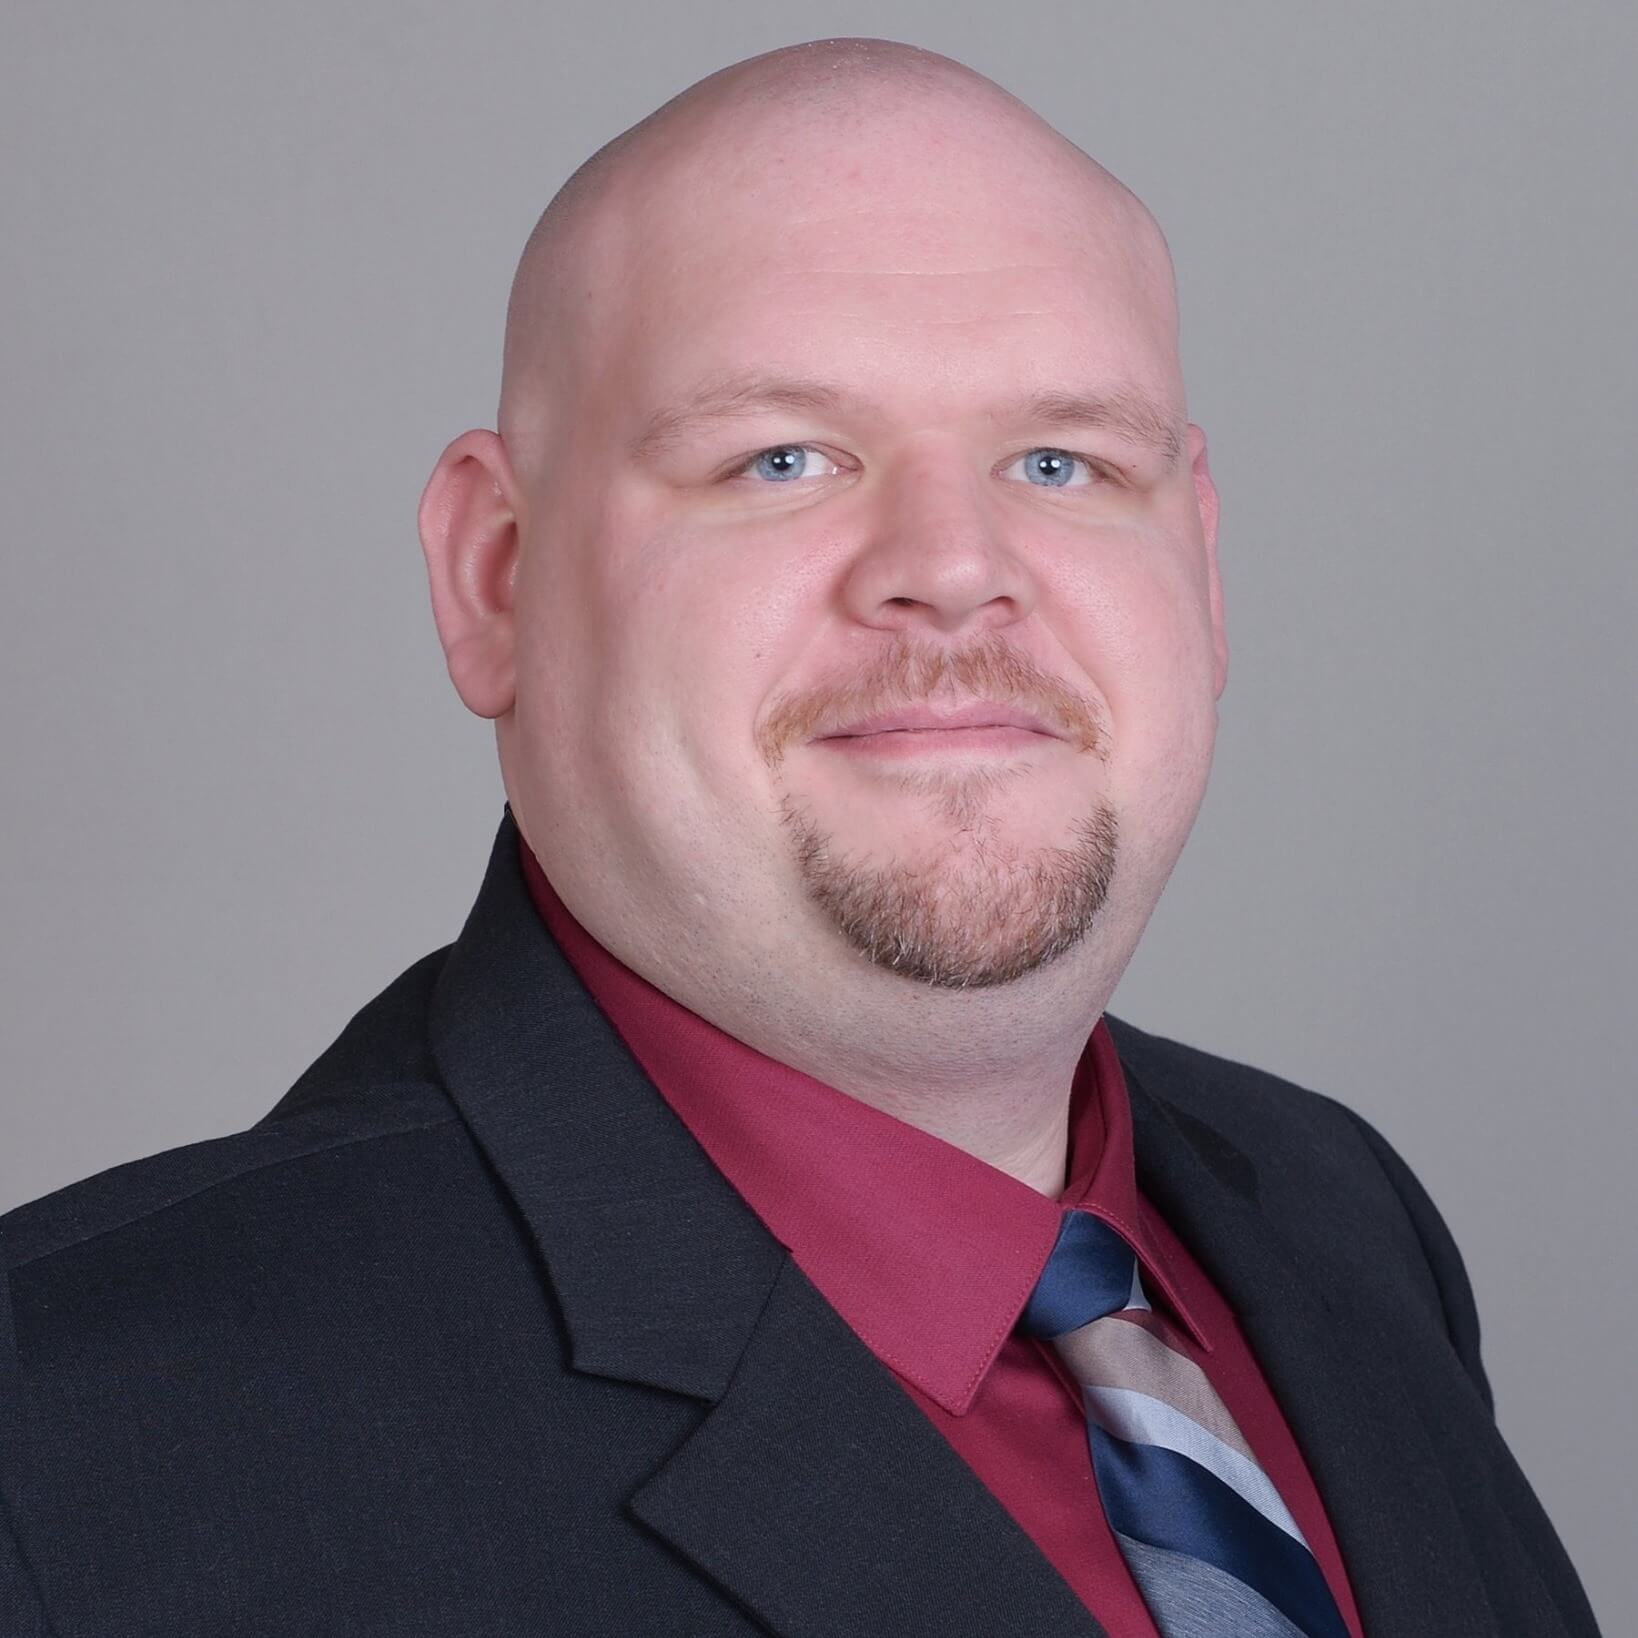
Six years running job costing and logistics inside construction, then a software company built and sold, before founding this firm. Degrees in Accounting and Computer Science alongside the MBA. Today CFO is a construction financial operations partner, not a CPA firm. Returns are prepared and reviewed by credentialed preparers on the team before they are filed.
You are booking time with him, not with a scheduler who hands you off afterwards.
Questions
It is a working call. Thirty minutes on your contracts, your retainage position and what your reporting currently produces. Nothing gets scoped or quoted off a conversation, so there is nothing to sign at the end of it. If it is obvious we are not a fit, the useful thing is to say that inside thirty minutes rather than book a second call.
Roughly what you have open, roughly what is being held in retainage, and the last pay application that came back if there was one. Estimates are fine. Nothing needs to be pulled from your accounting file for a first call.
If both sides want to keep going, the next step is the Financial Risk Assessment: free, 86 checkpoints run on your real books and your real contracts, with a findings call at the end. It is a required step before either side agrees to work together, not an upsell and not a package selector. The findings are yours whether or not you go further.
Yes. Plenty of contractors at this stage are not bonded, or were bonded once and did not enjoy it. Retainage, progress billing against a schedule of values, change orders and prequalification all arrive before a bond does, and they are what is costing you money now. If a bond request does come, the reporting that answers a prequal packet is most of what a surety asks for anyway.
No, and we are not a CPA firm. Your tax preparer files the return and reports what already happened. This is the finance function underneath it: monthly close, job costing, work-in-progress, retainage, pay applications and the compliance that comes with commercial work. Most contractors need both, and we will say so rather than push you to consolidate.
We are in Houston and we work with commercial contractors around the country. The contract reporting is the same wherever the job is. Certified payroll, prevailing wage and sales and use tax are state by state, and they get handled by locality.
That and your current contracts are enough for a first conversation. We will tell you what the retainage across them actually adds up to, what is stalling the billing, and whether this is worth paying anyone to fix yet. If it is not, we will say so.
Pick a time